VA & Military
A home loan benefit for some veterans, service members, and surviving spouses.
The Benefit, and the Loan Around It
A VA loan is a home loan benefit for eligible veterans, service members, and some surviving spouses. The Department of Veterans Affairs decides who can use it. That decision is a Certificate of Eligibility. A lender cannot grant it.
When the benefit fits, many buyers do not put money down. You can still owe closing costs, and the home still has to pass a VA appraisal. The loan is for a home you will live in, not a rental you will never occupy.
Many VA loans include a funding fee. Some veterans are exempt, including some with a service-connected disability. The fee can often be financed into the loan instead of paid in cash. A loan officer will say which case applies to your file. This page does not quote the fee.
The benefit can also be used to refinance a loan you already have. One version, often called an IRRRL, is a streamline refinance of an existing VA loan. It is a different file from a purchase, and it is not available on every VA loan.
In Everyday Language
A VA loan is a benefit for eligible veterans, service members, and some surviving spouses. The Department of Veterans Affairs decides who can use it. When it fits, it can help with the down payment. It is still a loan, with a review of income, credit, and the home.
A Benefit, and a Loan
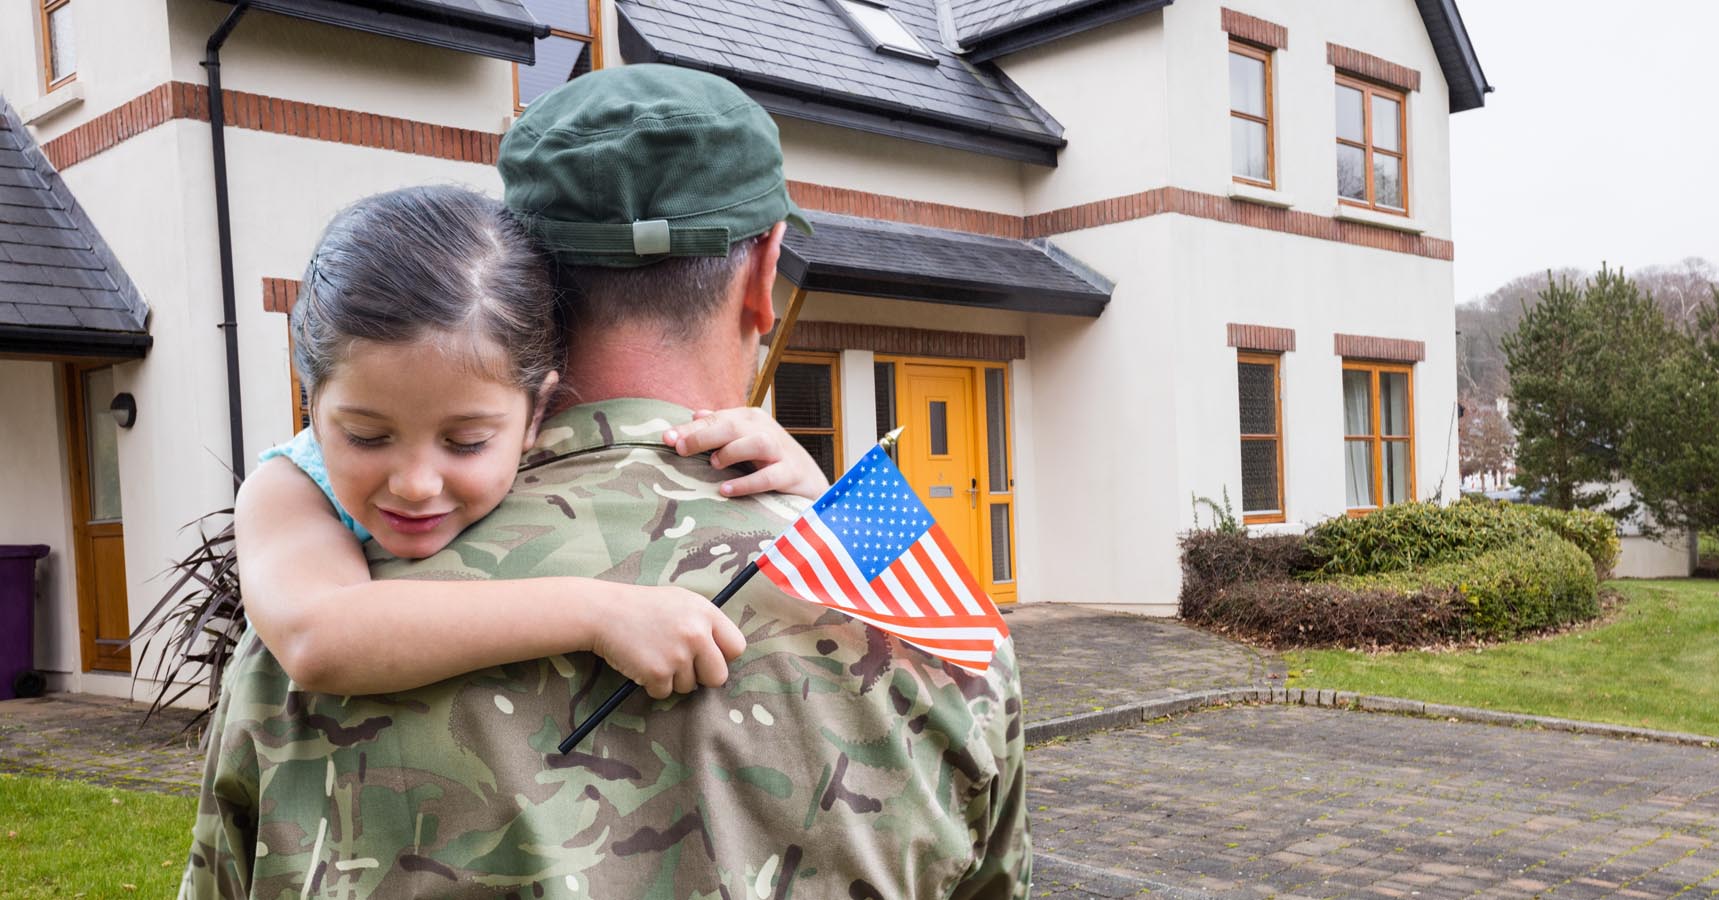
A VA loan is a benefit for eligible veterans, service members, and some surviving spouses. The VA decides who can use it. These photos are homes and families, not listings, and they are not an offer.
What the Benefit Covers
Eligibility, the home, the cash you bring, and a possible funding fee are separate questions. This page does not quote the fee.
Swipe sideways to see each part.
Who Can Use It
The VA reviews service history and entitlement. Military service by itself is not a yes. A lender cannot grant eligibility.
A Home You Will Live In
The loan is for a home you will occupy. A rental you will never live in does not fit.
Little or No Money Down
Many eligible buyers do not put money down. Closing costs and the home can still require cash.
A Purchase or a Refinance
The benefit can buy a home or, in some cases, refinance one you already have. A refinance is not always a lower payment.
The Funding Fee
Many VA loans include a funding fee. Some veterans are exempt. The fee can often be financed. This page does not quote it.
Who It Is Great For
- Eligible veterans, active service members, and surviving spouses
- Buyers who want to know whether their benefit can be used on this home
Who It May Not Fit
- People who do not have VA eligibility
- A home that will not be your primary residence
Key Requirements
01
Credit
A credit history a lender can review. Eligibility for the benefit is separate from the credit review.
02
Down Payment
Many eligible buyers do not put money down. Closing costs and the home itself can still require cash.
03
Debt-to-Income
Debts that fit the income you can document.
These notes describe topics a lender often reviews. They are not minimums or a promise of approval.
What to Remember
- The VA decides who can use the benefit
- Many VA loans do not require a down payment, and that is not a promise for every file
- The benefit can be used to buy or, in some cases, to refinance
Pros
- A benefit that can reduce the cash you need up front
- Can be part of a purchase or a refinance conversation
Cons
- You must be eligible, and the VA makes that call
- The home has to be one you will live in
How It Usually Goes
1
Confirm Eligibility
A Certificate of Eligibility, or the records used to request one, shows whether the benefit is available.
2
Choose the Home
Tell the loan officer if this is a purchase or a refinance of a home you already have.
3
Review Income and Credit
The benefit does not skip this step.
4
Close With the Numbers in Writing
Ask about any VA funding fee and whether you might be exempt before you compare payments.
1 of 4. Confirm Eligibility
Questions People Ask
Does Military Service Automatically Mean I Can Use a VA Loan?
No. The VA reviews service history and entitlement. A loan officer can help you request that review.
Can I Refinance With a VA Loan?
Sometimes. There are refinance options for eligible borrowers. They are not automatic, and they are not always a lower payment.
Related Calculators
Monthly Payment
Principal, interest, taxes, insurance, mortgage insurance, and HOA. You enter every number.
Affordability
Income, debts, and a down payment suggest a comfortable price range. It is a planning guide, not a pre-approval.
Refinance Break-Even
See the monthly difference and how long it takes for the savings to cover closing costs.