Investment & Commercial
Loans for rentals, short-term rentals, a portfolio of homes, and some small-business property needs.
Property You Will Not Live In
A loan on a rental follows different rules from a loan on a home you occupy. The review can look at the rent the property may earn, your cash reserves, and your credit. Vacancy, repairs, and local rental rules belong in the numbers. The loan does not guarantee that a tenant will pay.
These are the situations people usually mean:
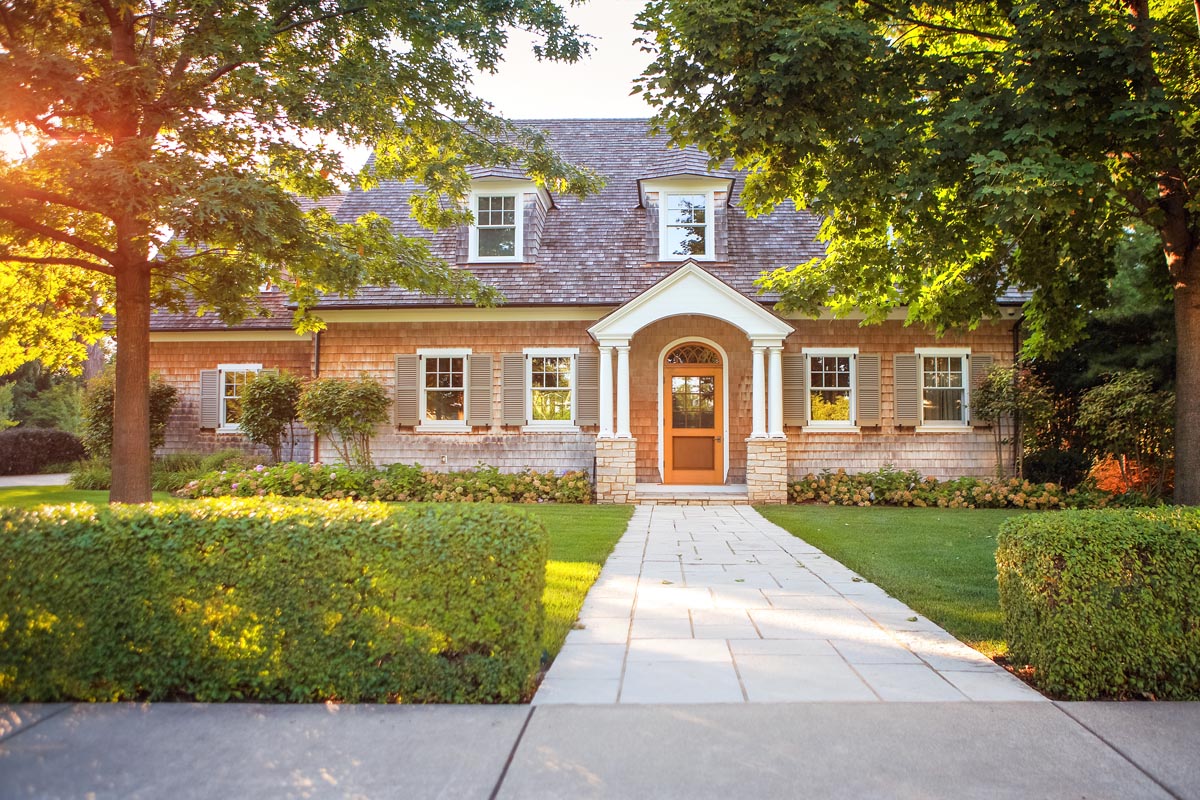
- A single-family home you will rent for the long term
- A short-term rental, when the city allows that use
- A small group of homes financed together
- A property you plan to renovate and sell
- A building with two to four units, which can be a different file from a larger apartment building
DSCR is the rent-to-payment ratio some of these loans use. It compares possible rent with the payment. It is one part of a review, not a yes or a no by itself.
A building a business occupies is a commercial conversation. Some of those loans use an SBA program. An SBA loan is for the business, not for a house you will live in as your home. A loan officer can tell you which desk should see the file.
In Everyday Language
A loan on a home you will not live in follows different rules. That includes a long-term rental, a short-term rental, and a small portfolio of homes. Lenders may look at the rent the property can earn, which investors call DSCR, as well as your income and savings. Commercial and SBA loans are a separate conversation for property a business uses. None of these is a promise that rent will cover the payment.
A Rental and a Workplace Differ
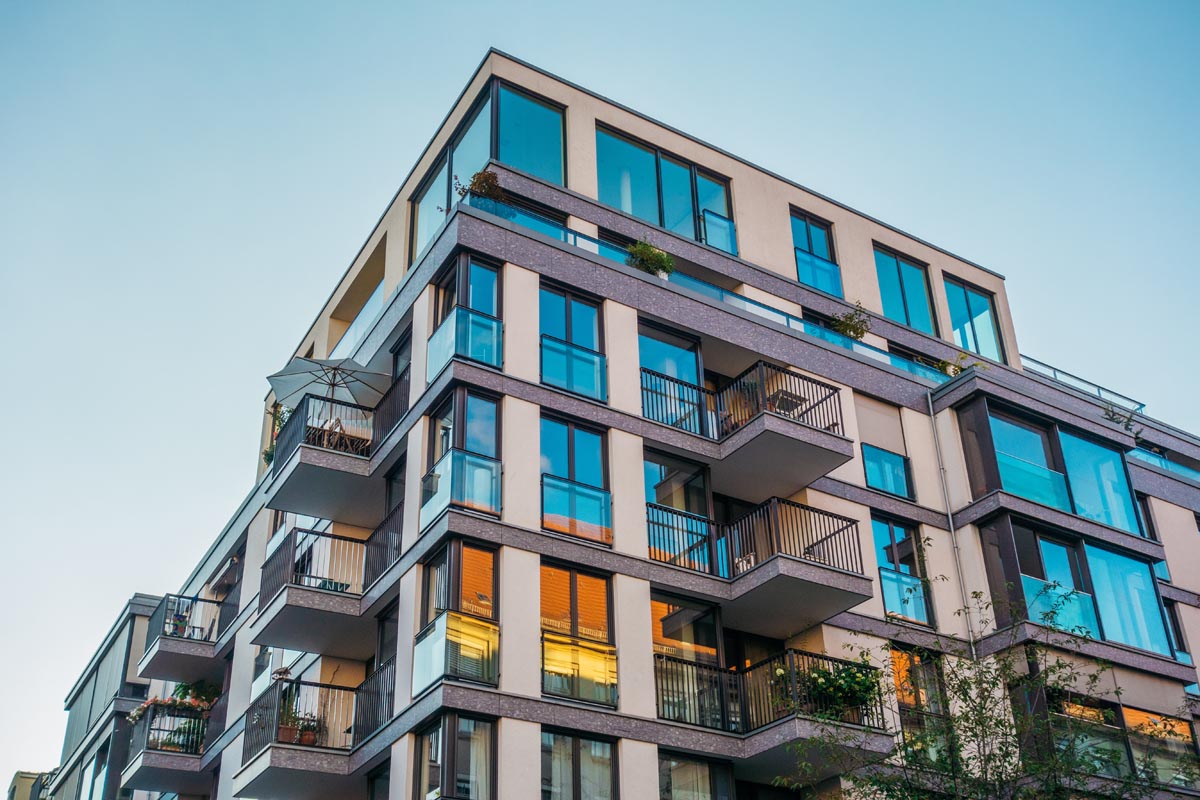
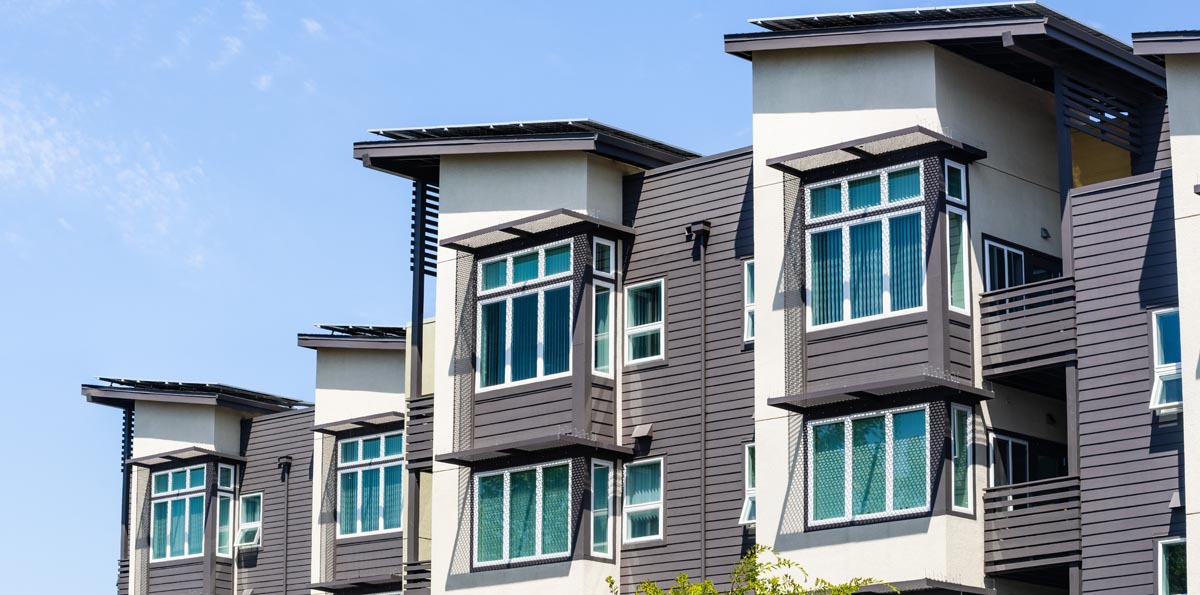
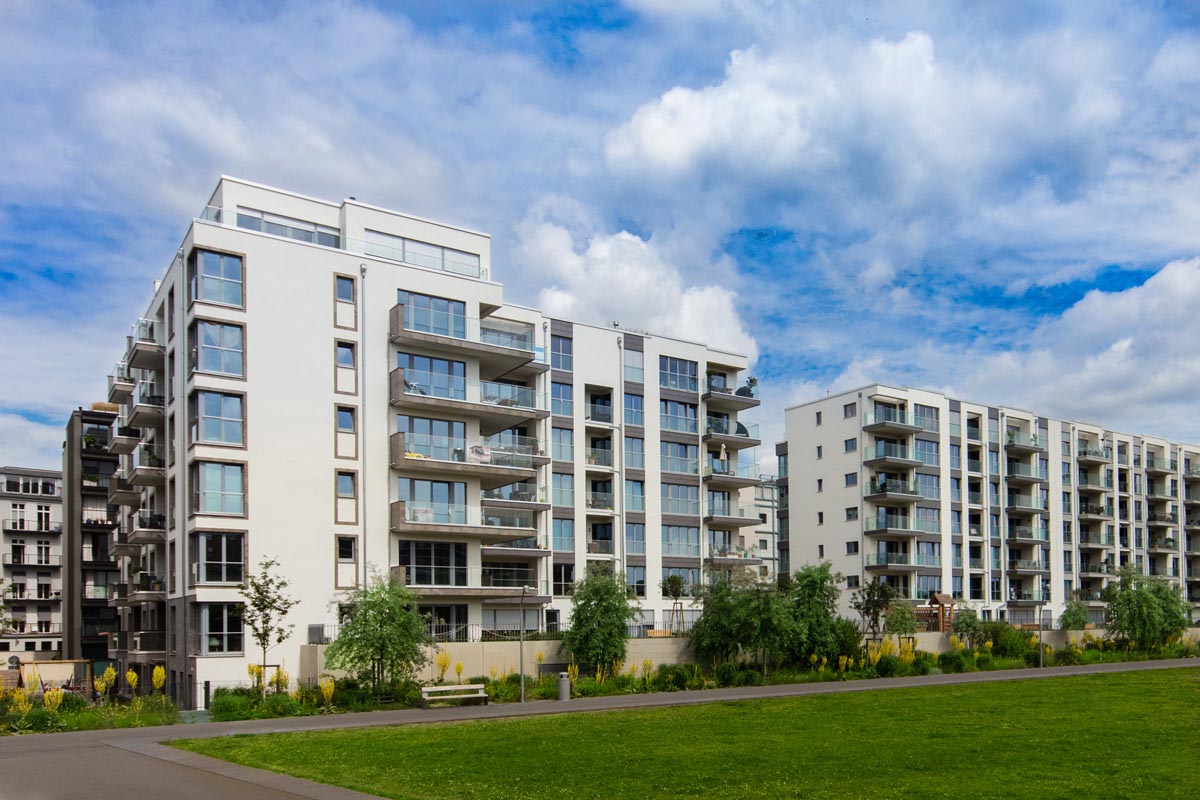
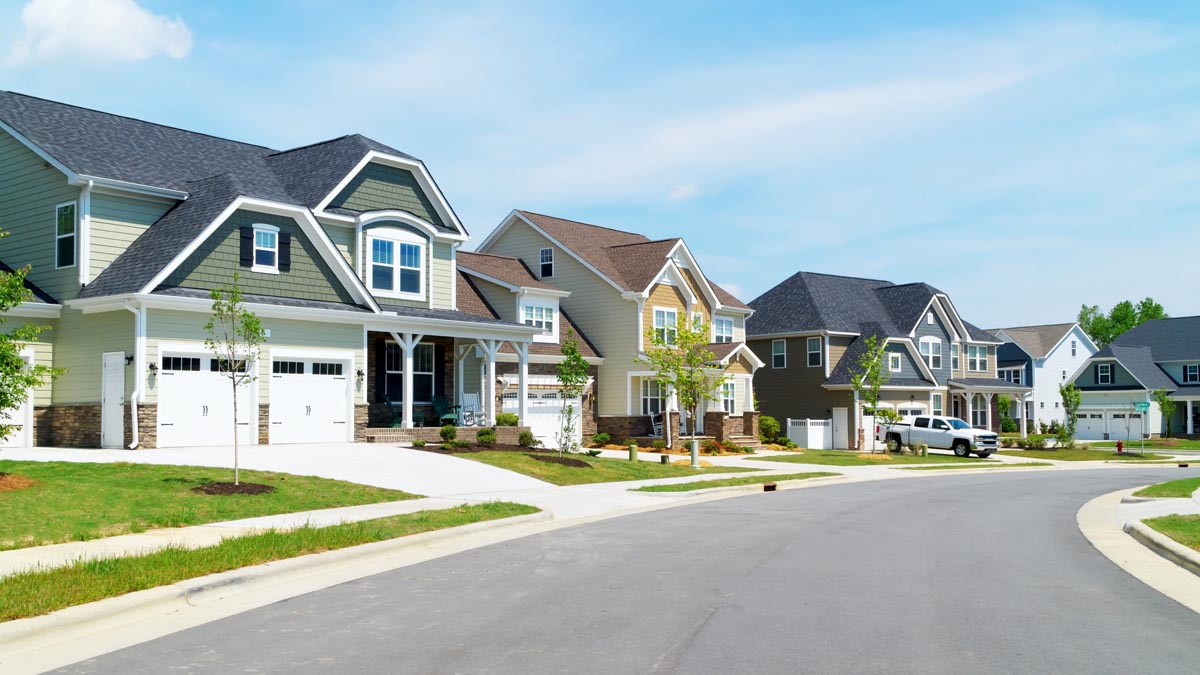
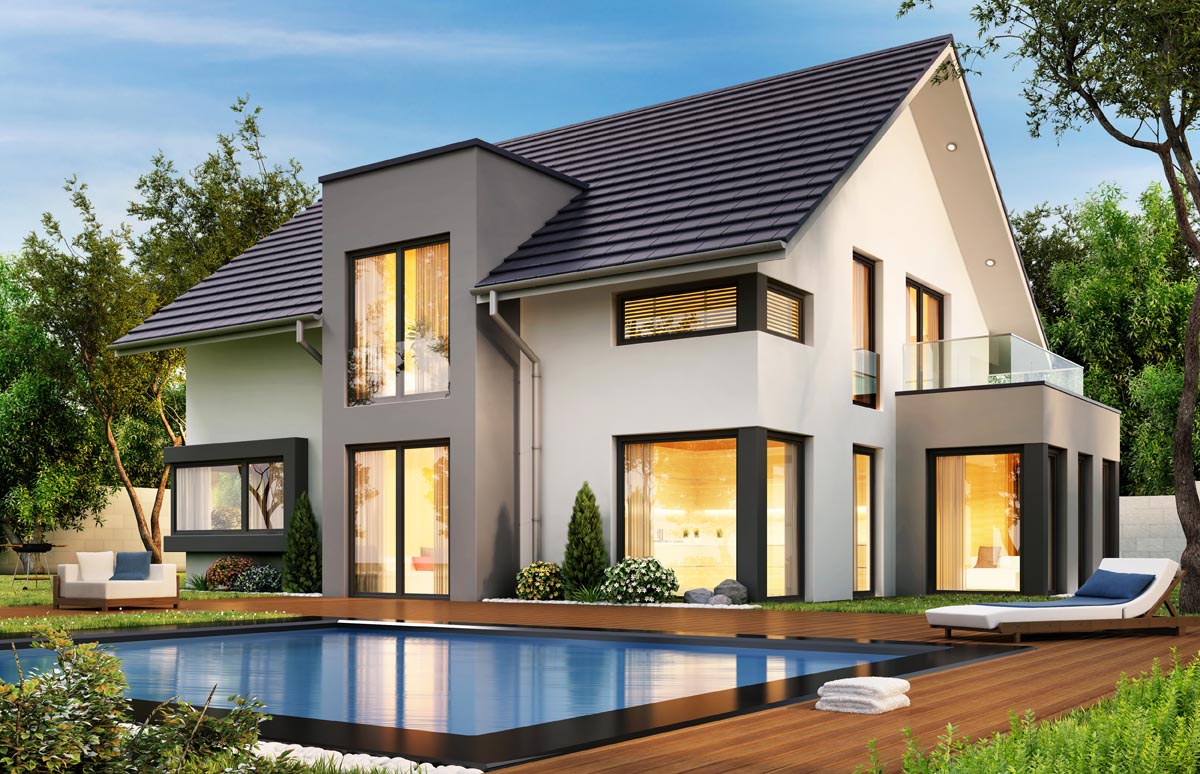
The loan follows the building. A home people rent and a place a business uses are not the same file. These photos show the kinds of property people ask about. They are not listings, and they are not an offer.
How the Property Is Used
Each use can change the cash, the reserves, and who reviews the file.
Swipe sideways to see each property.
A Few Homes in One Building
Two to four units can be a different file from a larger apartment property. How each unit is used matters.
A Row of Shops
Retail space can be occupied by the owner or leased out. Those two uses are not the same loan.
One Small Building
A single commercial building still needs a clear story. Who uses it, how it earns, and what cash is left after closing.
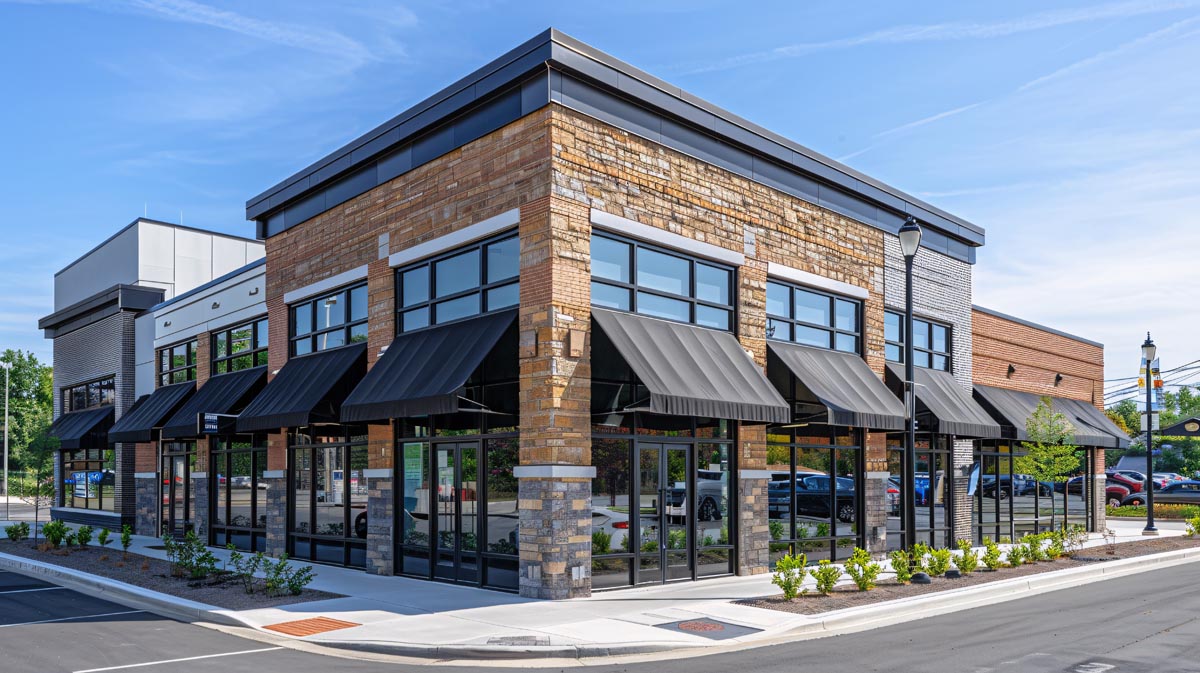
A Corner of Storefronts
A building a business occupies is a commercial conversation. Some of those loans use an SBA program. An SBA loan is for the business, not a house you will live in.
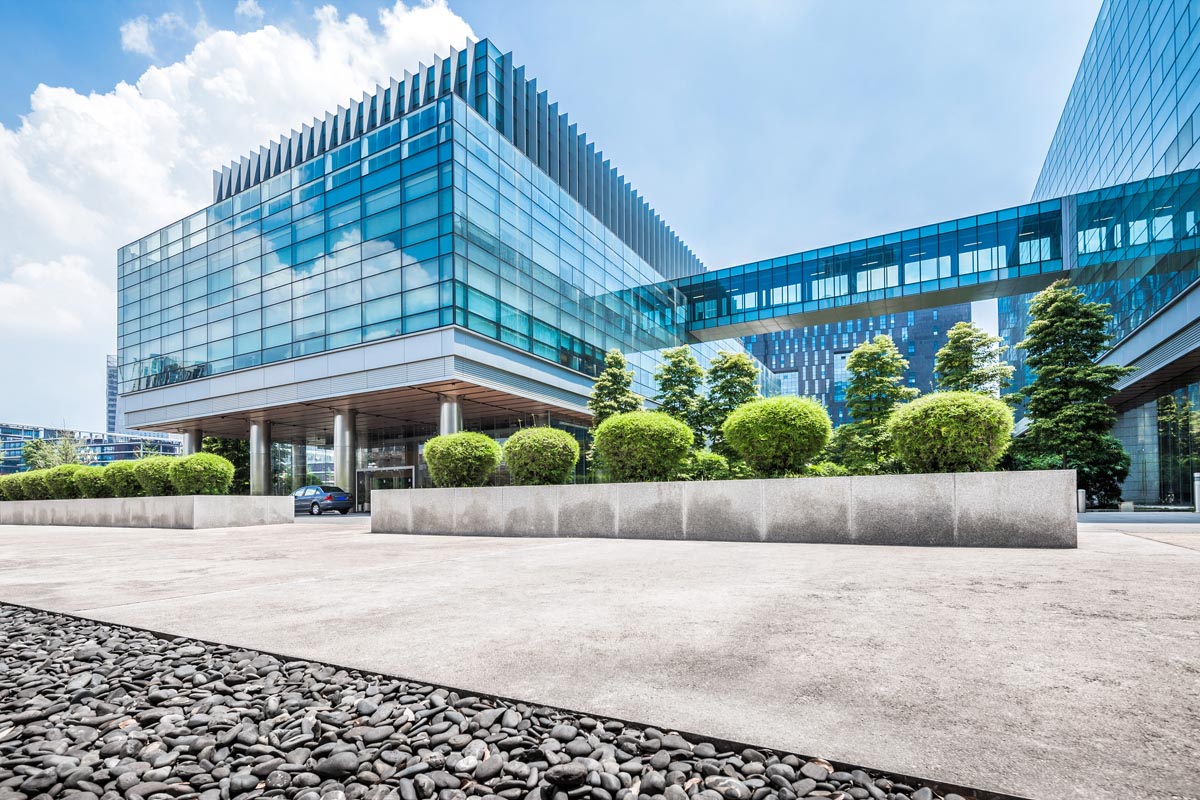
A Larger Workplace
A bigger building is still not a promise that rent will cover the payment. The business plan and the local rules belong in the file.
Who It Is Great For
- Buyers of a rental, including a short-term rental
- Investors adding another property to a small portfolio
- Business owners asking about an SBA or commercial property loan
Who It May Not Fit
- A primary home, which usually belongs in a purchase program
- Anyone who needs the rent to be guaranteed
Key Requirements
01
Credit
A credit history a lender can review. Investment loans are often looked at more strictly than a primary home.
02
Down Payment
A larger share of cash is common on a property you will not live in. The amount depends on the loan.
03
Debt-to-Income
Debts and income you can document. For some loans the rent-to-payment ratio matters as much as your personal debts.
These notes describe topics a lender often reviews. They are not minimums or a promise of approval.
What to Remember
- Different rules from a home you live in
- DSCR looks at rent compared with the payment
- SBA programs are for business property, not a typical house purchase
Pros
- A path for property you will not occupy
- Rent can be part of the story when the program allows it
Cons
- More cash and more reserves are common
- Vacancy, repairs, and short-term rental rules can change the numbers
How It Usually Goes
1
Say How the Property Will Be Used
A long-term rental, a short-term rental, and a building a business occupies are not the same loan.
2
Sketch Rent and the Payment
The investment calculator compares rent you enter with a payment you enter. It is not an approval.
3
Document Cash and Credit
Expect questions about savings left after closing.
4
Review Local Rental Rules
A city can limit short-term rentals. The loan does not override that.
1 of 4. Say How the Property Will Be Used
Questions People Ask
What Is DSCR?
It is a rent-to-payment ratio. It compares the rent the property may earn with the payment. It is one tool in a review, not a yes or a no.
Is an SBA Loan a Home Loan?
No. SBA programs are for small-business borrowing, including some owner-occupied commercial property. A house you will live in is a different file.