Conventional
A common loan for buying a home when you can document income, credit, and a down payment.
How a Conventional Loan Is Usually Used
A conventional loan is the path many people start with when they can show income, savings, and a credit history. It is not insured by the FHA, the VA, or the USDA. Lenders often use it for a home you will live in. A second home or a rental can use a conventional loan too, with different rules for cash and occupancy.
The loan can be a fixed rate or an adjustable rate. A fixed rate keeps the note rate the same for the term you choose. An adjustable rate can change later, on a schedule that is written into the loan. Ask which one you are looking at before you compare payments.
If the down payment is under 20 percent, private mortgage insurance is common. On many conventional loans that insurance can come off later, after the equity in the home is high enough. Removal is a review. It is not a date that arrives on its own.
On some files, a gift from family can count toward the cash you bring, and a seller can pay some of the closing costs. The lender still has to see where the money came from. A condo or a planned community can fit, as long as the building itself meets the program rules.
In Everyday Language
A conventional loan is a home loan that is not backed by a government program such as FHA, VA, or USDA. Many buyers start here when they have some money to put down and records that show their income.
A Loan Many Buyers Start With
A conventional loan is often the first path when you can show income, savings, and credit. These photos are homes, not listings, and they are not an offer.
Where This Loan Shows Up
The same loan name can cover different homes. The cash you bring, and how you will use the house, change the rules.
Swipe sideways to see each home.
A Home You Live In
Lenders often start here. You document income, savings, and credit, and the home still has to pass review.
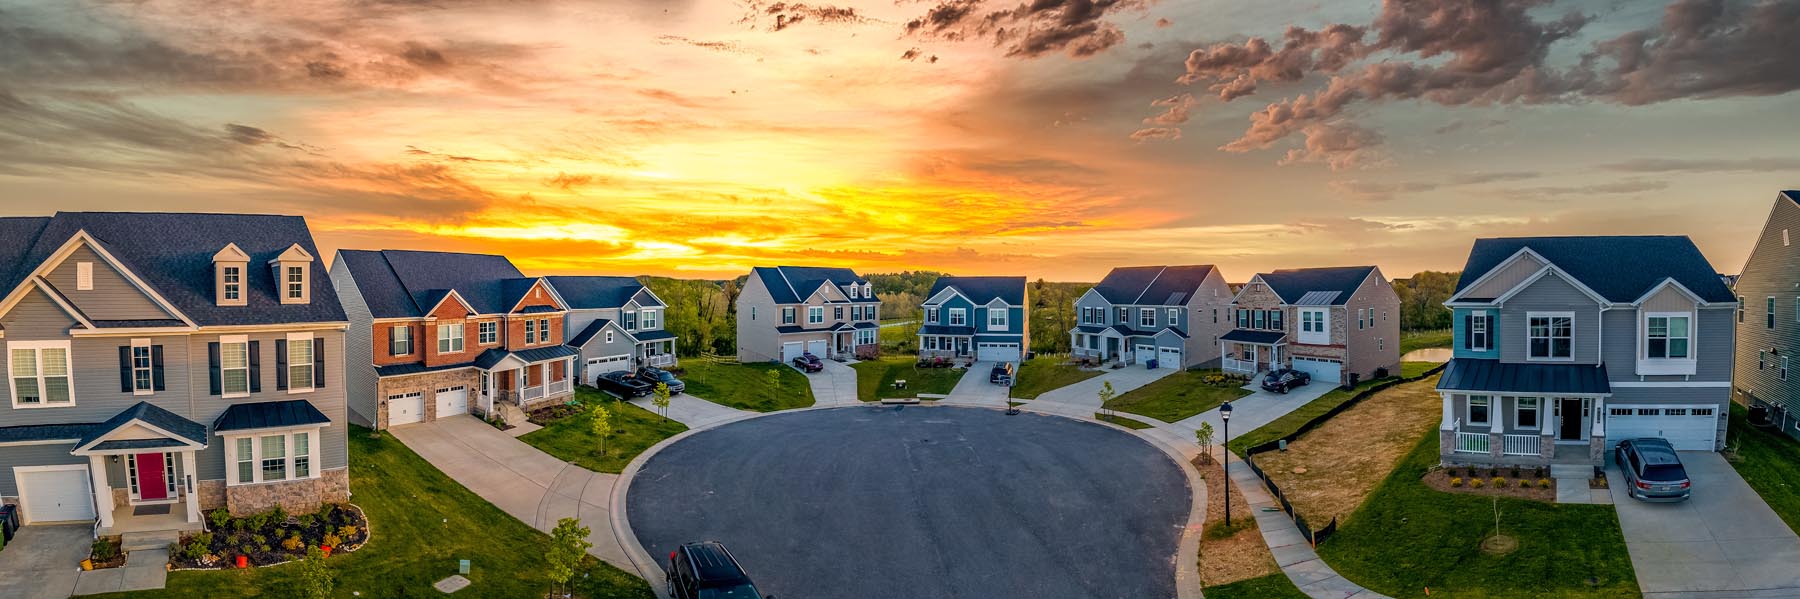
A Second Home
A house you visit, rather than live in full time, can use a conventional loan. The cash you bring is often higher.
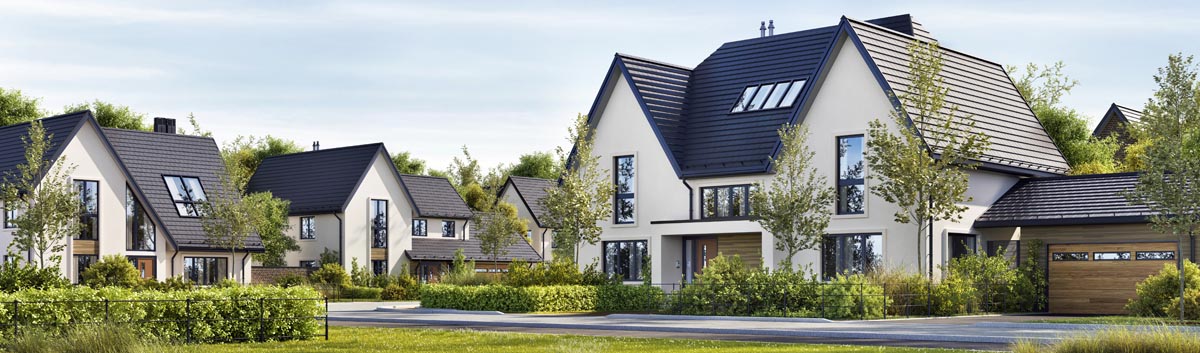
A Home You Will Rent
A rental can use a conventional loan too. Occupancy and cash follow different rules from a home you live in.
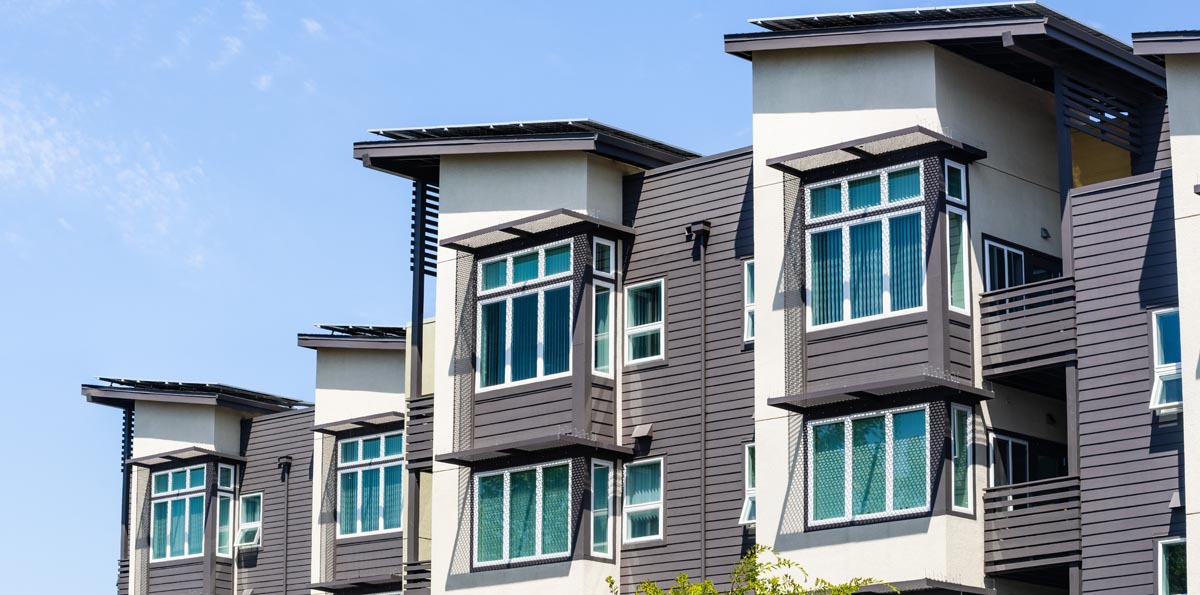
A Condo or Townhome
A condo or a townhome can fit when the building itself meets the program rules.
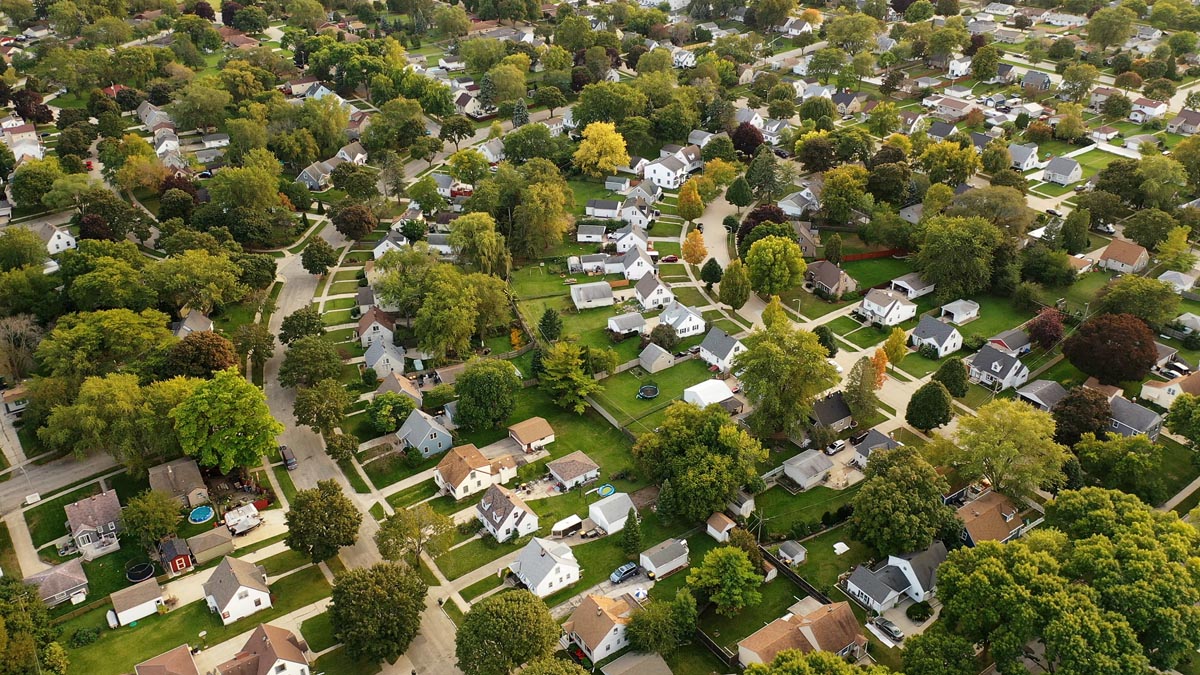
A Planned Community
Shared spaces and an association do not block the loan by themselves. The community still has to meet the rules.
Who It Is Great For
- Buyers who can document income and a down payment
- People buying a home they plan to live in
Who It May Not Fit
- Buyers who need a government-backed program to make the down payment work
- A home you will not live in, which follows different rules
Key Requirements
01
Credit
A credit history a lender can review. Stronger credit can open more choices. Fair credit does not decide the outcome by itself.
02
Down Payment
Some money down. How much depends on the loan, the home, and the rest of the file.
03
Debt-to-Income
Debts that fit the income you can document. Housing and other monthly bills are both part of that look.
These notes describe topics a lender often reviews. They are not minimums or a promise of approval.
What to Remember
- Not insured by a government program
- Often used for a home you will live in
- Still needs a full review of income, credit, and the home
Pros
- A familiar path for many home purchases
- Can fit a primary home when the file is complete
Cons
- A down payment is usually part of the conversation
- The home and your records still have to pass review
How It Usually Goes
1
Talk With a Loan Officer
Share what you want to buy and what you can document. This is a conversation, not an approval.
2
Gather Records
Income, savings, and credit are the usual starting records. The officer will say which ones matter for you.
3
Review the Home
The price, the appraisal, and the condition of the home are part of the file.
4
Close If the File Fits
You review the final numbers before you sign. You can ask what each cost is for.
1 of 4. Talk With a Loan Officer
Questions People Ask
Is a Conventional Loan the Same as a Government Loan?
No. Conventional loans are not insured by FHA, VA, or USDA. Those programs have their own rules.
Does This Page Mean I Will Be Approved?
No. It explains the idea. A loan officer reviews your full file before anyone talks about a decision.
Related Calculators
Monthly Payment
Principal, interest, taxes, insurance, mortgage insurance, and HOA. You enter every number.
Affordability
Income, debts, and a down payment suggest a comfortable price range. It is a planning guide, not a pre-approval.
Down Payment Planner
A savings timeline for the down payment you want.