FHA
A government-insured loan that some buyers use when a conventional loan is not the best fit.
What Makes an FHA Loan Different
An FHA loan is insured by the Federal Housing Administration. The insurance is there so a lender can work with buyers who have less cash saved, or a credit history that is still taking shape. It is used by first-time buyers and by people who have owned a home before.
The home has to be a place you will live in. It also has to meet a condition review. A fixer that needs major work may belong in a renovation conversation, not a standard FHA purchase.
FHA loans usually include mortgage insurance. How long you pay it depends on the size of the down payment and the rules in effect when the loan is made. That insurance is part of the monthly cost, so compare the full payment with a conventional loan, not only the note rate.
A later refinance of an FHA loan is sometimes called a streamline. It can be a shorter file when you already have an FHA loan and you are not taking cash out. It is still a new loan, and it still has costs.
In Everyday Language
An FHA loan is insured by the Federal Housing Administration. The insurance helps some buyers qualify when a conventional loan is a stretch. You still have to document income, credit, and the home. The insurance is not free. It is usually part of the payment.
A Path When Conventional Is a Stretch
FHA insurance can help when savings or credit make a conventional loan a poor fit. You still document income, credit, and the home. These photos are homes, not listings, and they are not an offer.
What the Review Looks At
The insurance does not skip the file. Cash, credit, occupancy, the condition of the house, and the monthly cost all still come up.
Swipe sideways to see each part.
Less Cash Saved
The down payment is often smaller than on a conventional loan. You still need money for that payment and for closing costs.
Credit Still Taking Shape
Past problems do not automatically end the conversation. They also do not guarantee a yes. A lender still reviews the history.
A Home You Will Live In
The house has to be a place you will live in. A rental is a different loan.
The Condition of the House
The appraisal looks at safety and condition, not only the price. A fixer that needs major work may belong in a renovation conversation.
Insurance in the Payment
Mortgage insurance is usually part of the monthly cost. Compare the full payment with a conventional loan, not only the note rate.
Who It Is Great For
- Buyers who have some savings but not a large down payment
- People whose credit needs a closer look than a standard conventional file
Who It May Not Fit
- Buyers who want to avoid mortgage insurance
- A property that does not meet the program's condition rules
Key Requirements
01
Credit
A credit history a lender can review. Past problems do not automatically end the conversation, and they do not guarantee a yes.
02
Down Payment
A smaller down payment than many conventional loans. You still need money for the down payment and for closing costs.
03
Debt-to-Income
Debts that fit the income you can document. Other monthly bills matter as much as the new house payment.
These notes describe topics a lender often reviews. They are not minimums or a promise of approval.
What to Remember
- Insured by the Federal Housing Administration
- Often part of a first-home conversation
- Mortgage insurance is usually part of the loan
Pros
- Can help when savings or credit make a conventional loan a poor fit
- A well-known program with published rules
Cons
- Mortgage insurance is commonly part of the cost
- The home has to meet condition rules
How It Usually Goes
1
See If FHA Is Even the Right Conversation
A loan officer compares it with conventional and with any down-payment help in your area.
2
Document Income and Savings
Pay records, tax records, and bank statements are the usual start.
3
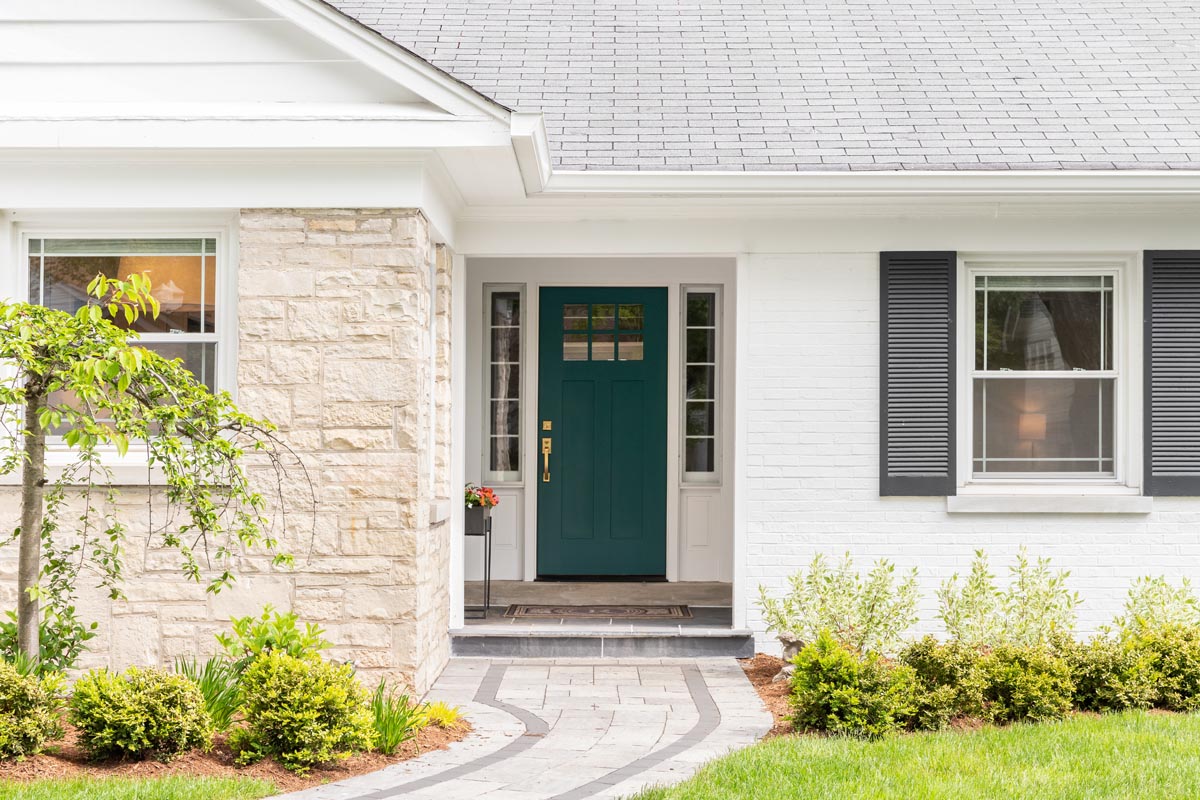
Check the Home
An FHA appraisal looks at safety and condition, not only the price.
4
Review the Insurance and the Payment
Ask how mortgage insurance changes the monthly cost before you decide.
1 of 4. See If FHA Is Even the Right Conversation
Questions People Ask
Is FHA Only for First-Time Buyers?
No. First-time buyers use it often, and so do people who have owned a home before.
Does FHA Insurance Mean the Loan Is Approved?
No. The insurance protects the lender. Your file and the home still have to be reviewed.
Related Calculators
Monthly Payment
Principal, interest, taxes, insurance, mortgage insurance, and HOA. You enter every number.
Affordability
Income, debts, and a down payment suggest a comfortable price range. It is a planning guide, not a pre-approval.
Down Payment Planner
A savings timeline for the down payment you want.
From the Learning Center
Related Programs
Conventional
A common loan for buying a home when you can document income, credit, and a down payment.
First-Time Buyers
A plain-English path for people buying a home for the first time, or for the first time in a long while.
Down Payment Assistance
Local and state programs that may help with the cash you need to buy, when you and the home qualify.
A Real Conversation
Ready When You Are.
Talk with a loan officer who is licensed where the home is. Walk through buying, refinancing, or a loan that does not fit a standard file. Start with the directory, or answer a few questions first.